Dwelling (Coverage A)
The cost to rebuild your home at today's local labor and material prices. We recommend extended replacement cost so a regional spike does not leave you short.
Personal lines
Dwelling, contents and liability coverage built around Kansas City's hail, wind and older housing stock.
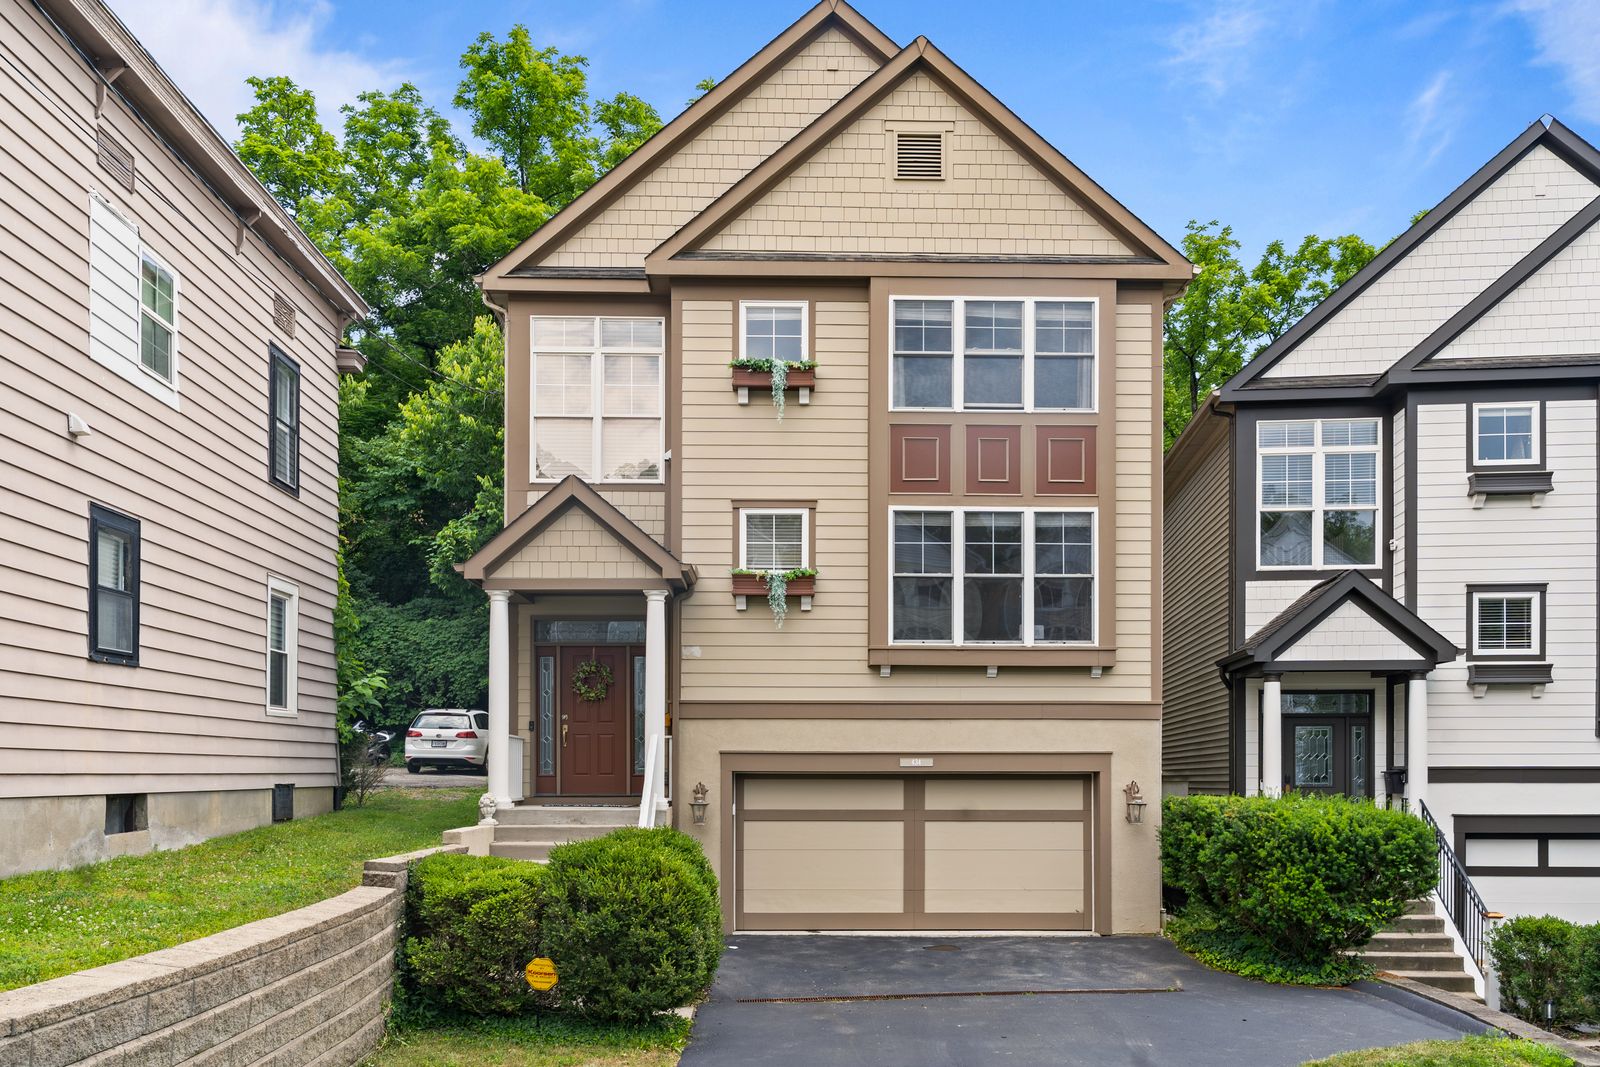
Overview
Kansas City sits in one of the busiest hail corridors in the country, and most local homeowners policies now carry a separate wind and hail deductible written as a percentage of the dwelling limit. If you do not know your percentage, you do not know your real out-of-pocket cost.
We rebuild the dwelling limit from current local construction costs rather than the purchase price, because a 1924 bungalow in Waldo with plaster walls and a slate roof costs far more to rebuild than it costs to buy.
The coverages we build into every quote, plus the endorsements that matter in this metro.
The cost to rebuild your home at today's local labor and material prices. We recommend extended replacement cost so a regional spike does not leave you short.
Detached garages, fences, sheds and that pergola you added last summer, usually 10 percent of the dwelling limit.
Contents coverage, written on replacement cost rather than actual cash value so a ten-year-old sofa is not settled at scrap value.
Hotel, rental and restaurant costs above your normal spending while the house is uninhabitable.
Injuries on your property or caused by your household, including the dog, subject to breed rules that vary by carrier.
Water backup, service line, equipment breakdown, ordinance or law, and scheduled items for rings, instruments and firearms.
Four steps from your current policy to a better-fitting one.
Roof age, electrical panel, plumbing type, square footage and any recent updates. Fifteen minutes on the phone is usually enough.
We run a replacement-cost estimate and compare it with what your current policy carries.
Some carriers love older homes with updated systems. Others surcharge them heavily. We know which is which.
We pair the winner with your auto policy where the combined price wins, then set your renewal review.
Coverages that overlap with this one, or fill the gap it leaves.
All coverage Auto insuranceLiability, collision and uninsured motorist coverage written for how Missouri and Kansas drivers actually commute.
 Umbrella insuranceAn extra million or more of liability sitting above your auto and home policies, for surprisingly little.
 Condo insuranceHO-6 coverage that fills the gap between your association's master policy and what you actually own.
If your question is not here, call the office. You will reach a licensed agent in Kansas City, not a queue.
It is a deductible calculated as a share of your dwelling limit rather than a flat dollar amount. On a $400,000 dwelling limit, a 2 percent hail deductible means the first $8,000 of a hail claim is yours. We always convert it to dollars for you.
Not unless you add water backup coverage. It is one of the least expensive endorsements available and one of the most common claims in older Kansas City neighborhoods.
Usually not. Claims under or near your deductible rarely pay out and can affect your rate and eligibility for years. Call us first and we will tell you honestly whether filing helps.
Yes, though fewer carriers will offer replacement cost on the roof at that age. Several will write actual cash value instead. We will show you the difference in plain dollars before you decide.
Send us your current declarations page and we will shop fourteen carriers, then tell you plainly whether moving is worth it.
No fee for our work. No obligation to switch. Usually a same-day written comparison.
We value your privacy
We use cookies to run this site, remember your preferences and understand how it is used.Cookie policy