Commercial property
Building if you own it, plus equipment, inventory, furniture and tenant improvements if you lease.
Business lines
Property, general liability and business income bundled for Kansas City shops, offices, studios and contractors.
Overview
A business owners policy, or BOP, packages the three things almost every small business needs: coverage for your stuff, coverage for claims against you, and coverage for the income you lose when you cannot operate.
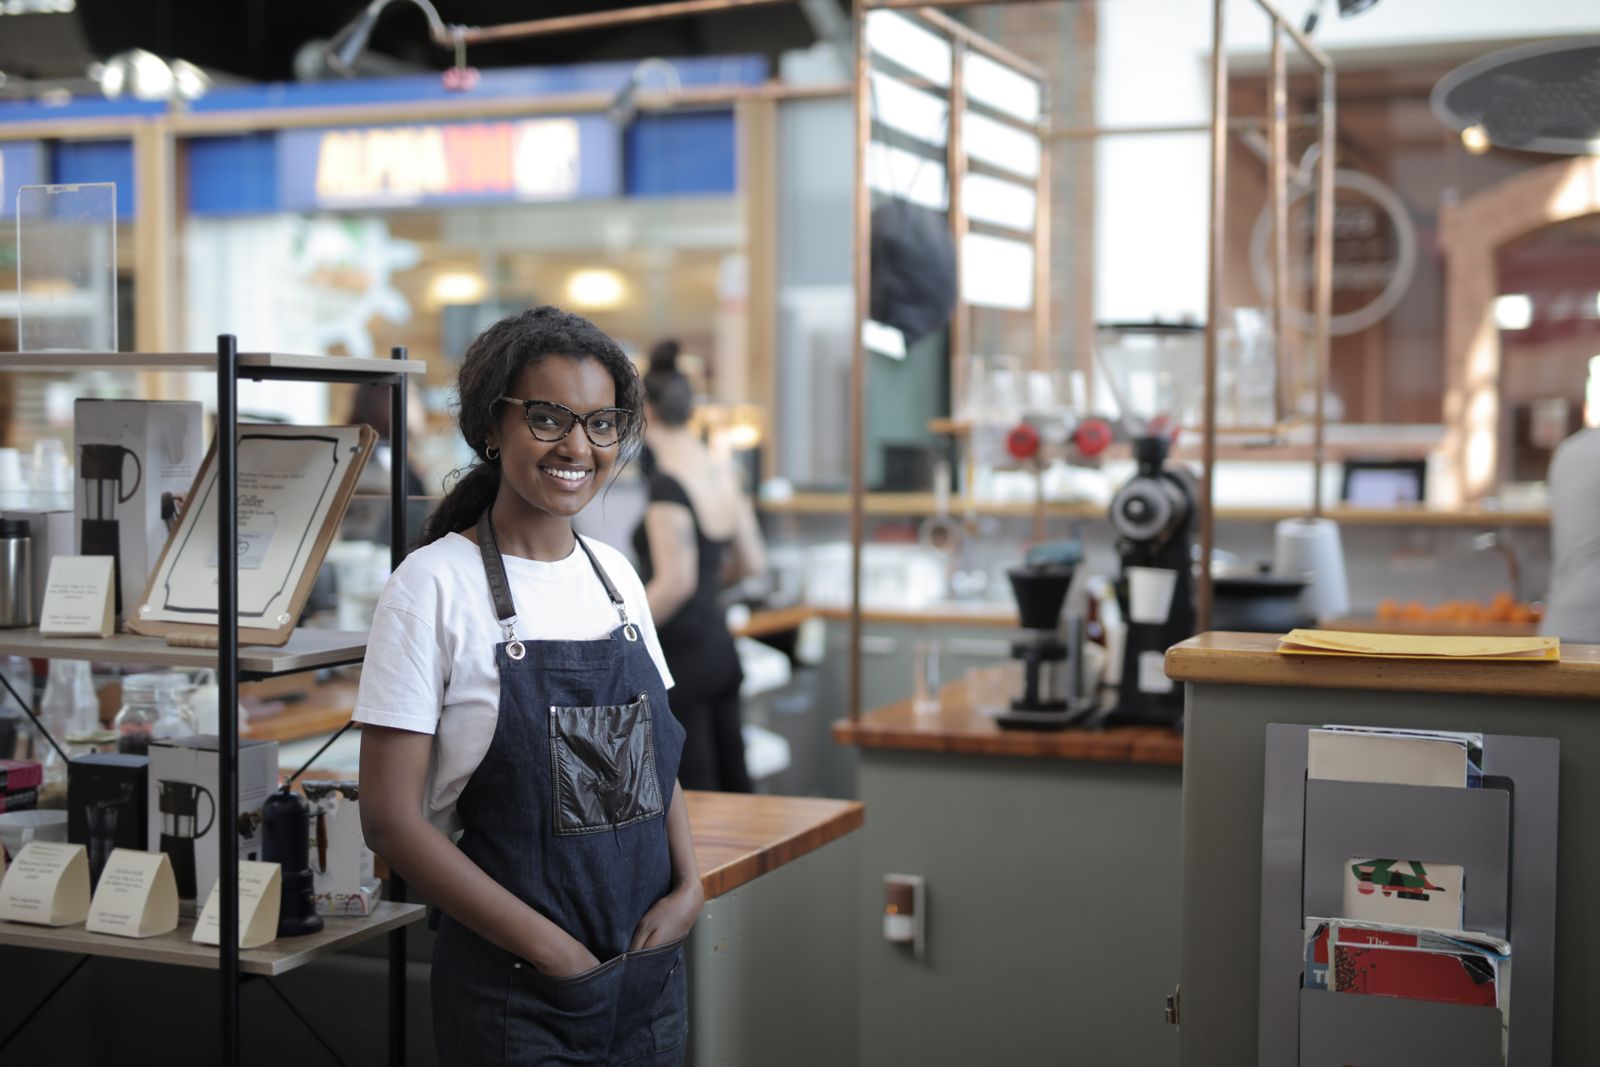
We write BOPs for restaurants in the Crossroads, dental practices in Leawood, contractors in the Northland and consultancies working out of a spare bedroom. The right carrier depends heavily on your class code, and independent shopping is the only way to find it.
The coverages we build into every quote, plus the endorsements that matter in this metro.
Building if you own it, plus equipment, inventory, furniture and tenant improvements if you lease.
Third-party bodily injury and property damage, including the slip-and-fall claims that dominate retail and hospitality.
Replaces lost profit and covers temporary relocation while you are shut down after a covered loss.
Mechanical and electrical failure of HVAC, refrigeration, POS systems and production equipment.
Breach response, notification costs and extortion coverage, now available as an endorsement at most carriers.
Errors and omissions coverage for advice-giving and service businesses, added alongside the BOP.
Four steps from your current policy to a better-fitting one.
Your class code drives eligibility and price. Getting it right is half the job.
Equipment, inventory, tenant improvements and a realistic business income figure based on your last twelve months.
Some carriers want restaurants, others will not touch them. We know current appetite across our fourteen companies.
Landlords, clients and general contractors get their certificates from us the same day, every time.
Coverages that overlap with this one, or fill the gap it leaves.
All coverage Commercial autoVehicles, trailers and hired or non-owned exposure for trades, delivery fleets and service businesses.
 Workers' compensationRequired coverage for Missouri and Kansas employers, placed with carriers that know your class codes.
 Umbrella insuranceAn extra million or more of liability sitting above your auto and home policies, for surprisingly little.
If your question is not here, call the office. You will reach a licensed agent in Kansas City, not a queue.
Yes if you have business equipment, client visits or professional exposure. Homeowners policies sublimit business property severely and exclude business liability almost entirely.
A one-page proof of coverage that landlords, clients and general contractors require. We issue them during office hours, usually within an hour of the request.
We start with twelve months of net profit plus continuing expenses such as rent and payroll, then choose a restoration period long enough to rebuild and reopen.
Most commercial policies are auditable on payroll or revenue. We set realistic estimates up front so your audit is a formality rather than a surprise bill.
Send us your current declarations page and we will shop fourteen carriers, then tell you plainly whether moving is worth it.
No fee for our work. No obligation to switch. Usually a same-day written comparison.
We value your privacy
We use cookies to run this site, remember your preferences and understand how it is used.Cookie policy