Coverage
Nine coverages, one independent agency
Personal and commercial lines shopped across fourteen carriers, with the differences explained in dollars rather than jargon.
What we write
Personal lines
Your house, your cars, your family and the liability that sits over all three.
Start a quote Auto insuranceLiability, collision and uninsured motorist coverage written for how Missouri and Kansas drivers actually commute.Sample: $92/moDetails
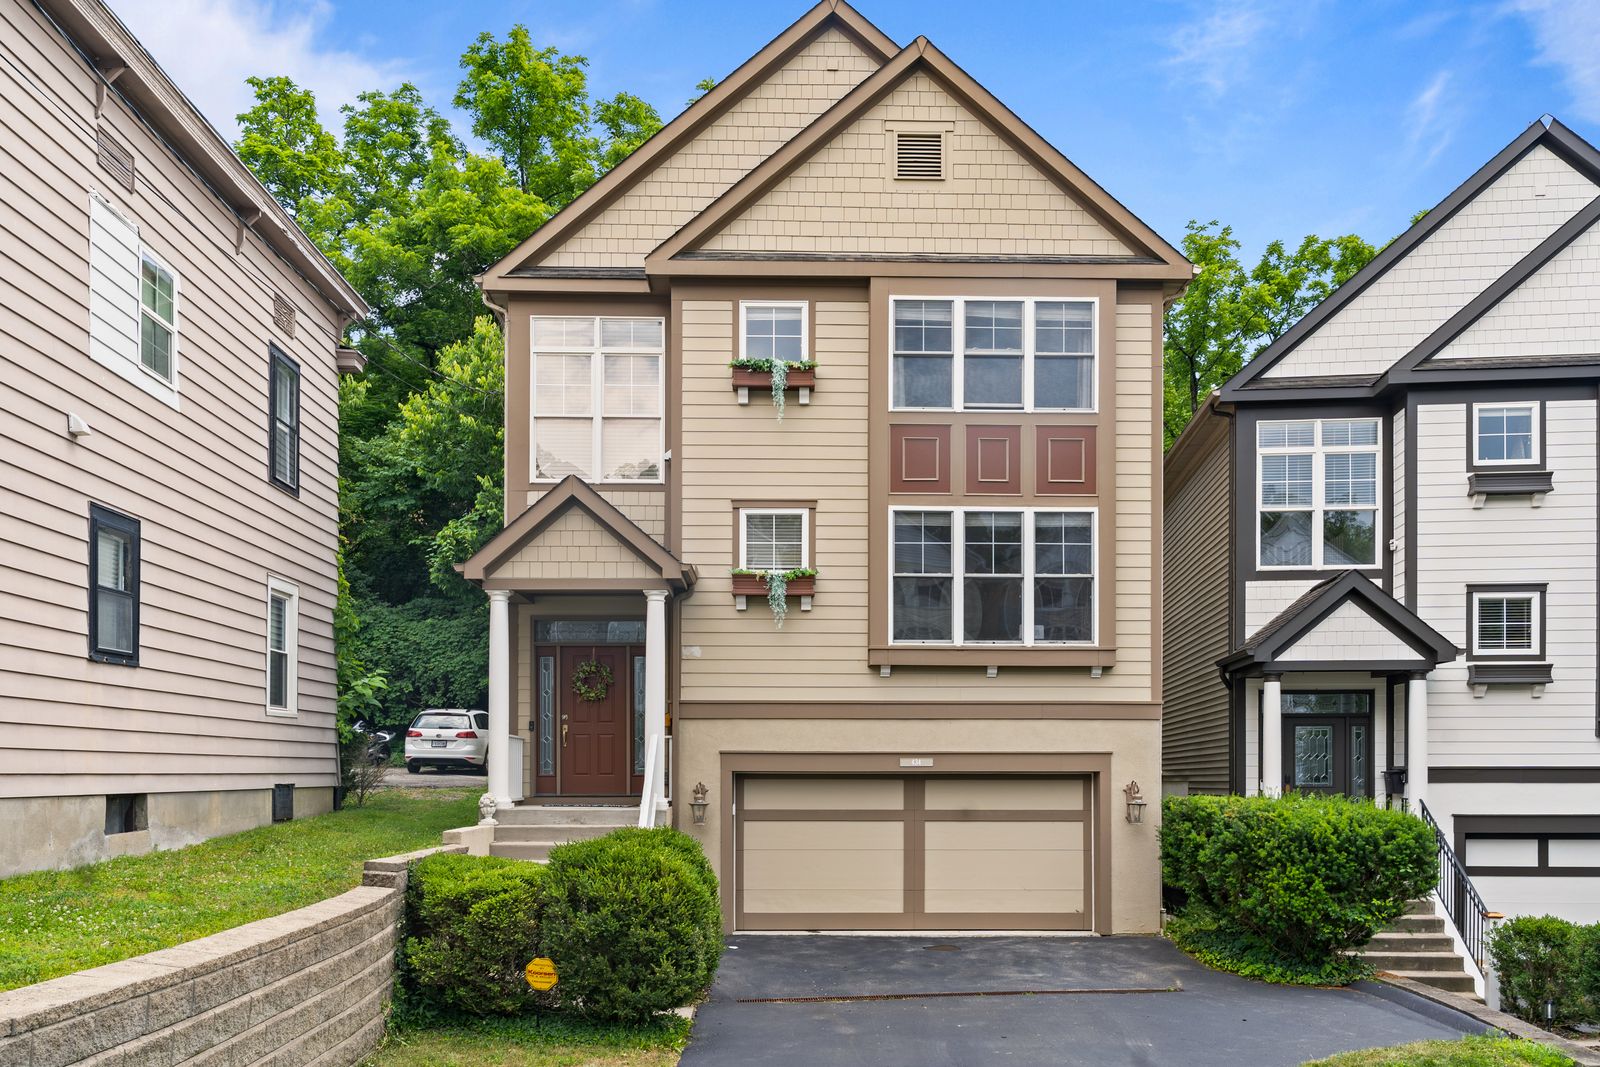 Home insuranceDwelling, contents and liability coverage built around Kansas City's hail, wind and older housing stock.Sample: $148/moDetails
 Renters insuranceBelongings, liability and temporary living costs for apartments and rental houses, often for less than a streaming bundle.Sample: from $14/moDetails
 Condo insuranceHO-6 coverage that fills the gap between your association's master policy and what you actually own.Sample: $41/moDetails
 Life insuranceTerm, whole life and final expense policies sized with a real needs calculation instead of a round number.Sample: $38/moDetails
 Umbrella insuranceAn extra million or more of liability sitting above your auto and home policies, for surprisingly little.Sample: $21/moDetails
Business lines
Coverage for Kansas City shops, offices, studios, trades and the crews who run them.
Start a quote Business owners policyProperty, general liability and business income bundled for Kansas City shops, offices, studios and contractors.Sample: $118/moDetails
 Commercial autoVehicles, trailers and hired or non-owned exposure for trades, delivery fleets and service businesses.Sample: $186/mo per vehicleDetails
 Workers' compensationRequired coverage for Missouri and Kansas employers, placed with carriers that know your class codes.Sample: rated per $100 payrollDetails
Fourteen carriers compete for your policy
Meet the carriersCarrier names shown are fictional samples for this demo. Appetite and availability vary by ZIP code and risk.
Coverage basics
Questions about what is actually covered
If your question is not here, call the office. You will reach a licensed agent in Kansas City, not a queue.
As a floor, enough to protect what you could lose. For homeowners in this metro we usually recommend 100/300/100 on auto and $500,000 of personal liability on the home policy, then an umbrella above both if you have savings, equity or a professional income.
Most Kansas City homeowners policies now apply a separate deductible for wind and hail damage, written as a percentage of the dwelling limit. On a $400,000 dwelling limit, a 2 percent deductible means $8,000 comes out of your pocket first. We always convert it to dollars so there are no surprises.
No. Rising water is excluded from every standard homeowners policy. Flood coverage is a separate policy through the NFIP or a private flood market, and we can quote both. Water backup from a drain or sewer is different again and is added by endorsement.
Replacement cost settles a claim at what it costs to buy the item new today. Actual cash value subtracts depreciation first. The difference on a ten-year-old roof or a five-year-old sofa can be thousands of dollars, so we confirm which basis your policy uses.
Yes. The landlord's policy covers the building, not your belongings and not your liability. Renters insurance is usually the least expensive policy in this office, and most leases in the metro now require it.
Tell us what you own
Send your current declarations page and we will show you, line by line, where your coverage is thin and where you are paying for something you do not need.
No fee for our work. No obligation to switch. Usually a same-day written comparison.