Car accident
Safety first, then police, then photos of all vehicles and the scene. Exchange insurance details. Do not accept fault at the scene.
Claims center
Everything before this is paperwork. When something happens, you get a 24/7 intake line and a named advocate in our Kansas City office who owns the file until it closes.
Four situations we handle constantly in this metro, and the first moves that protect your claim.
Safety first, then police, then photos of all vehicles and the scene. Exchange insurance details. Do not accept fault at the scene.
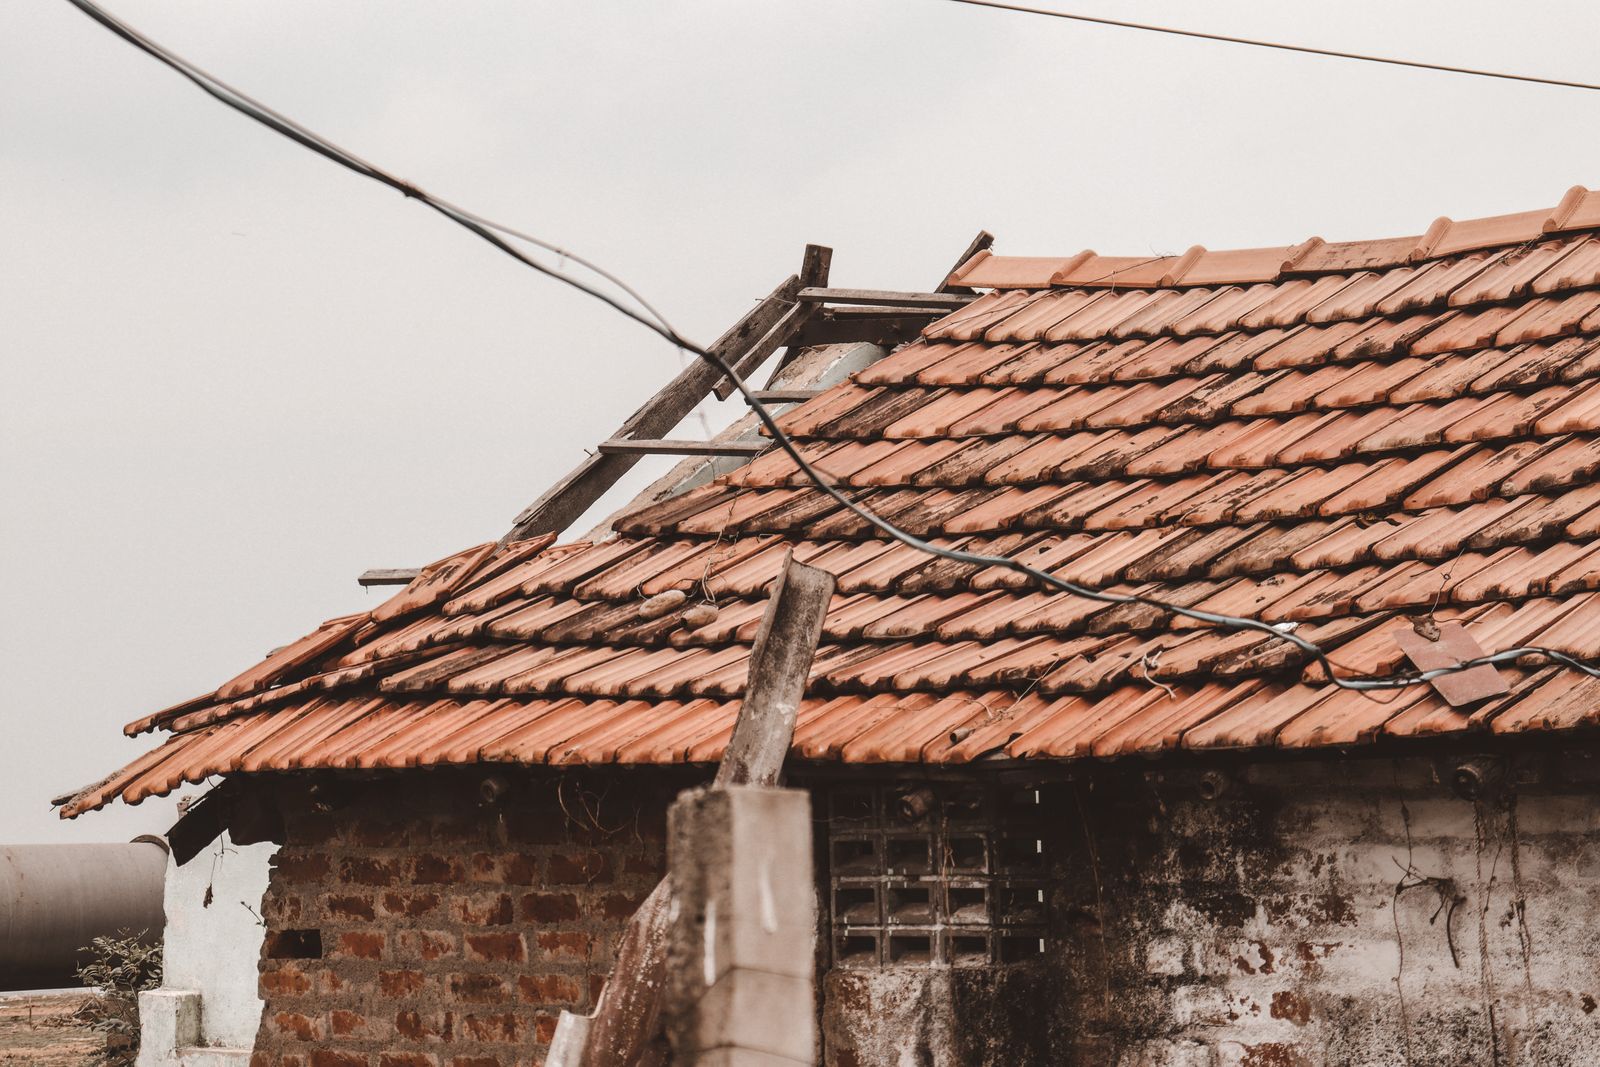
Photograph the roof line from the ground, the gutters and any dented vents or screens. Keep receipts for emergency tarping.
Stop the source if you safely can, then photograph before removing anything. Save damaged items until the adjuster has seen them.
File a police report first; nearly every carrier requires the report number. Then list what is missing with model numbers if you have them.
How a claim runs
Carriers own the claim decision. We own making sure nothing about your file gets lost in it.
Any hour, any day. After hours you reach the carrier's intake team, and a Clearpath advocate picks up the file the next business morning.
Photos of every angle, the police report number if there is one, and a written list of what was damaged before anything is moved.
We tell you what to expect, what to point out and what not to sign. If the scope looks thin, we say so before you accept it.
We track the estimate, the supplements and the final payment, and we chase the file if it goes quiet.
Before you call
You do not need all of them to start a claim. The more you have, the faster the first payment moves.
Claims
If your question is not here, call the office. You will reach a licensed agent in Kansas City, not a queue.
Call either. Our 24/7 claims line routes to the carrier intake team after hours, and a Clearpath advocate picks up your file the next business morning. Calling us first means someone local is tracking the claim alongside you.
Often not. A claim close to or below your deductible rarely pays anything meaningful and can affect your rate and eligibility for three to five years. Call us before you file and we will walk through the math honestly.
After a widespread storm, adjuster scheduling is the bottleneck. A typical roof claim in this market runs three to six weeks from inspection to final payment, longer when contractors are booked out. We chase the file so you do not have to.
Make sure everyone is safe, call the police, photograph all vehicles and the scene, and exchange insurance information. Do not accept fault at the scene. Then call our claims line, day or night.
It depends on fault and claim type. Comprehensive claims such as hail and theft are usually weighted more gently than at-fault collisions. If your renewal does rise, that is the moment we reshop your policy across our other carriers.
The claims line runs 24 hours a day, 365 days a year. During office hours you will reach the same people who wrote your policy.
Sample response times shown are illustrations for this demo, not a service guarantee.
We value your privacy
We use cookies to run this site, remember your preferences and understand how it is used.Cookie policy